
Design-Build Strategy
Built on Experience, Powered by Local Partnerships
Insights
A Financial Institution Executive’s outline for a specialized design-build partner.
Financial institutions face increasing pressure to modernize their physical environments while maintaining operational efficiency, regulatory compliance, security, and strong community relationships. Successful branch transformation requires more than conventional construction expertise; it demands a strategic understanding of how branch design influences consumer engagement, staff productivity, advisory interactions, and long-term institutional growth. Organizations that specialize exclusively in financial institution design-build projects bring a distinct advantage by combining banking-specific experience with disciplined execution.
When your design-build partner focuses on integrating compliance, accessibility, security, operational performance, and evolving consumer expectations into every phase of planning and construction, institutions can create branch environments that support current objectives while positioning themselves for future growth. The combination of specialized financial expertise and local market knowledge provides a framework for delivering facilities that strengthen both institutional performance and community impact.
Local trades held to banking standards
We partner with vetted local contractors and suppliers while keeping their work on-spec for a financial environment.
Compliance and ADA handled by specialists
Banking-specific infrastructure, security, and accessibility standards are designed in from day one, not left for a generalist to interpret.
Spend that stays in your community
Using local businesses keeps project dollars in the market you serve, which matters to the consumers behind it.
Market knowledge from people who live there
Local partners understand permitting, labor, and site conditions; we add branch strategy tuned to financial institutions.
Layouts built around branch performance
Concierge placement and consumer flow are planned to support deposit growth, engagement, staffing efficiency, and cross-selling.
Designed for what’s next
Spaces that account for evolving generational preferences and the shift toward advice-based, technology-enabled banking.
Tailor-Made Design-Build Solutions for Financial Institutions
Because we build only for financial institutions, every lesson from every branch carries forward to yours – operational layout, security, compliance, and the design decisions that quietly shape performance. At the same time, the work happens through local businesses who know your market and live in your community. That pairing – specialized expertise with local execution – keeps your project on-spec, keeps spend close to home, and gives you a partner who understands both the institution and the place it serves.
Financial Institutions Stats
to
Branch expansion intent among financial institutions increased from 29% to 35% year-over-year, indicating continued investment in physical banking environments.
U.S. retail and small business deposits totaled approximately $9.5 trillion, with a 0.4% increase between June 2023 and June 2024.
U.S. retail and small business deposits achieved a 2.6% compound annual growth rate over four years, reinforcing the continuing importance of branch-driven relationship banking.
Frequently Asked Questions
What branch network models are delivering the strongest performance today?
There is no single model that works in every market. A hub-and-spoke network can give financial institutions a practical mix of full-service hubs, smaller branches, ITMs, and digital access. The right combination depends on local demand, the services people need in person, and the cost of serving each market.
What demographic data should drive branch placement decisions?
Look beyond population growth alone. Household and business growth, income, commuting patterns, existing account holder locations, competitor presence, and demand for lending or advisory services can all help identify opportunities. Market analysis can then guide whether a location needs a full-service hub, a smaller spoke, or another service option.
How should financial institutions balance branch investment with digital transformation initiatives?
Plan physical and digital access together. Digital tools can make routine transactions more convenient, while branches provide space for personal guidance and more complex conversations. A hub-and-spoke strategy lets financial institutions invest in a strong physical presence where it matters most and use smaller, technology-enabled locations elsewhere.
How does a hub-and-spoke strategy affect efficiency ratios?
Smaller spokes may reduce the space and staffing needed to serve additional markets, which can help control operating costs. The effect on an institution’s efficiency ratio depends on both costs and revenue, however. Financial institutions should evaluate each location’s projected expenses alongside deposit, lending, and relationship growth before expecting a specific improvement.
What role do ITMs play in staffing optimization?
ITMs can handle many routine transactions with remote teller support, giving account holders access to help without requiring a full teller team at every location. They can be useful in smaller spokes or markets where a traditional branch footprint is difficult to justify. Staffing decisions should still reflect transaction volume and the need for in-person advice.
Contact Altitude
Ready to experience The Altitude Approach? Contact us today. We’re excited to learn about your next project and how we can help bring it to life.
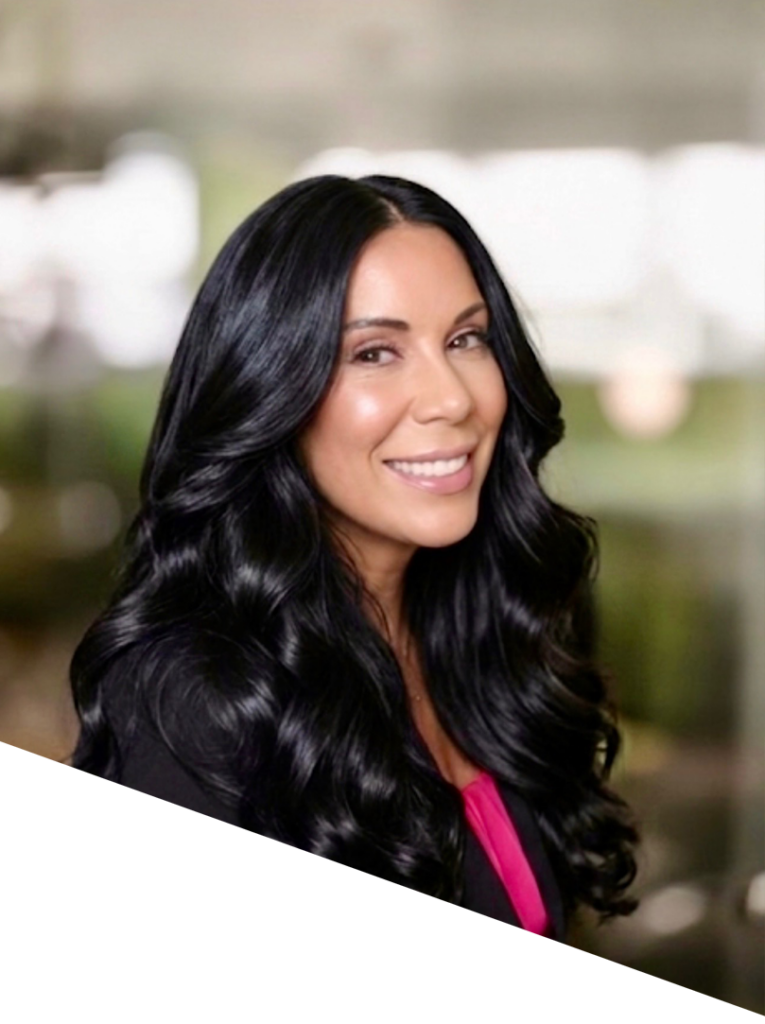
Chief of Staff
Yolanda Chavez
About:
Yolanda Chavez is the Chief of Staff of Altitude, bringing more than 10 years of experience in the banking industry. A dynamic and visionary executive, she serves as a trusted strategic partner to the President and CEO, supporting company growth by driving alignment, execution, and follow-through on priority initiatives.